
Regional Trends: A Look at the Midwest
While the national outlook is decidedly grim, the HMI data reveals significant regional variations. On a three-month moving average basis, all four major U.S. regions posted lower scores in October, but some areas are proving more resilient than others.
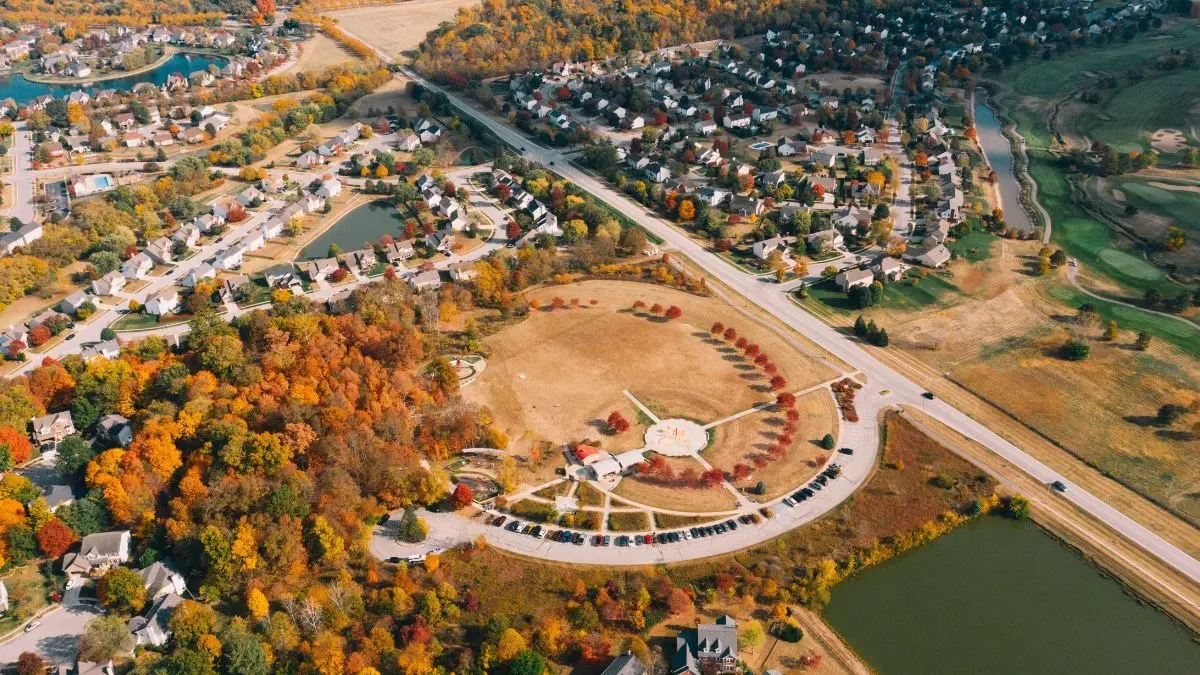
The Midwest has emerged as a relative bright spot for the single-family construction industry. While other regions have seen a sharp pullback in activity, building permits in the Midwest actually rose by 2.9%, according to NAHB data. This resilience can be attributed to several factors. First, land costs in the Midwest are generally lower than in the coastal metros of the West and the Northeast, allowing builders more room to offer incentives without completely erasing their margins.
Second, many Midwestern markets face less severe regulatory burdens than their counterparts in the high-priced coastal regions. This allows for a faster "dirt-to-door" timeline, reducing the amount of time a builder is exposed to the risks of fluctuating interest rates and material costs. In contrast, the West and Northeast continue to struggle with high entry costs and a regulatory environment that often adds years to the development process.
The South, which has been the powerhouse of American homebuilding for the last decade, is also seeing a cooldown. While it remains the most active region in terms of total volume, the sheer scale of development in states like Florida and Texas means that the impact of rising rates is being felt across a massive number of active projects.
The Path Ahead for the Housing Market
As the industry moves toward the final months of the year, the focus for homebuilders has shifted from growth to stability. The data from the October HMI serves as a clear signal to policymakers and economists that the housing sector—a traditional engine of the U.S. economy—is under significant duress.
The persistent demand for housing, driven by a decade of underbuilding and a large generation of Millennials entering their prime home-buying years, provides a theoretical floor for the market. However, as Chief Economist Robert Dietz noted, demand cannot be realized if affordability remains out of reach. The "squeeze" currently being felt by builders and buyers alike is unlikely to ease until there is a stabilization in mortgage rates and a resolution to the supply-side constraints that continue to drive up the cost of new construction.
For now, the industry remains in a defensive posture, relying on incentives and strategic pricing to navigate a landscape that hasn’t looked this challenging in over twelve years. The transition from a "seller’s market" to one defined by builder concessions and buyer hesitation appears to be complete, leaving the future of the 2024 housing market dependent on the broader trajectory of the American economy.