These minor sacrifices are part of a broader trend across the United Kingdom. Children’s pensions, formally known as Junior Self-Invested Personal Pensions (SIPPs), were first introduced to the UK financial market in 2001. Under current tax regulations, parents, grandparents, or guardians can contribute up to £2,880 per year into a Junior SIPP. The government then tops up these contributions with 20% tax relief, adding up to £720 annually to bring the total maximum investment to £3,600 per year.
Over the last few years, the popularity of these accounts has surged. Financial institutions and investment platforms report a significant rise in the number of parents utilizing Junior SIPPs to build generational wealth.

For instance, the investment platform Hargreaves Lansdown reported that in the 12 months leading up to April 2026, the number of newly opened Junior SIPP accounts was two and a half times higher than the figure recorded during the previous 12-month period. Similarly, rival investment service Fidelity reported that its number of active Junior SIPP accounts had more than tripled since December 2023.
For families who can afford to set aside money early, the long-term projections are compelling. Jemma Slingo, a pensions specialist at Fidelity, highlights how even small, consistent contributions can snowball over time due to compounding.
"Paying in £50 a month from birth, including tax relief, the family would contribute £10,800 over those 18 years," Slingo notes. "The pot could grow to around £135,000 by retirement. That’s the real power of starting early – relatively modest amounts can have an exceptionally long time to compound."
‘I want to retire earlier so this will help’
While parents are often highly motivated by the prospect of securing their children’s financial futures, the children themselves must eventually come to terms with holding assets they cannot touch for half a century. For some teenagers, however, the concept of a long-term nest egg is highly reassuring.
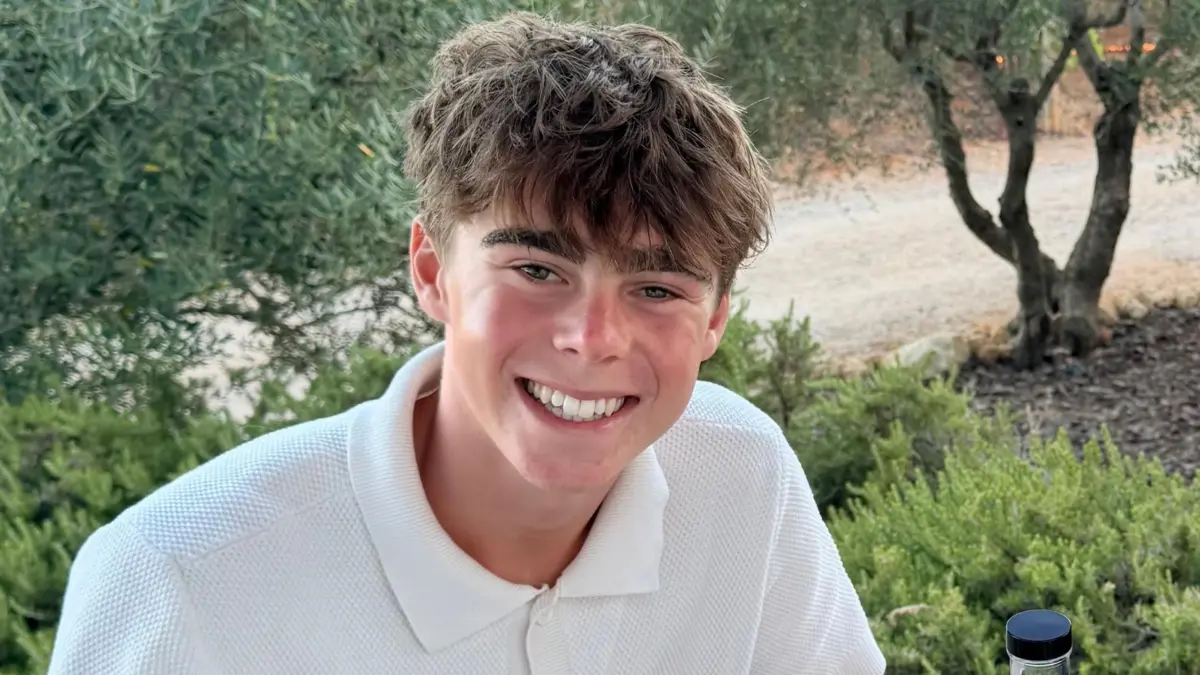
Fifteen-year-old Hugo Thompson, who lives in Manchester, is entirely comfortable with the restriction. His parents, both of whom work in the financial services sector, have been contributing the maximum allowable amount into his Junior SIPP for the past decade.
"The money invested means perhaps I’ll be ahead when I’m older," Hugo says. "So I won’t have to put quite so much of my own money in! I want to retire earlier than the state pension age so this will all help."

Hugo’s mother, Annabel, also maintains a Junior ISA to assist him with his transition into adulthood. However, she emphasizes that the decision to fund a child’s pension should not come at the expense of a parent’s own financial health. She continues to prioritize her own pension contributions and personal savings alongside Hugo’s accounts.