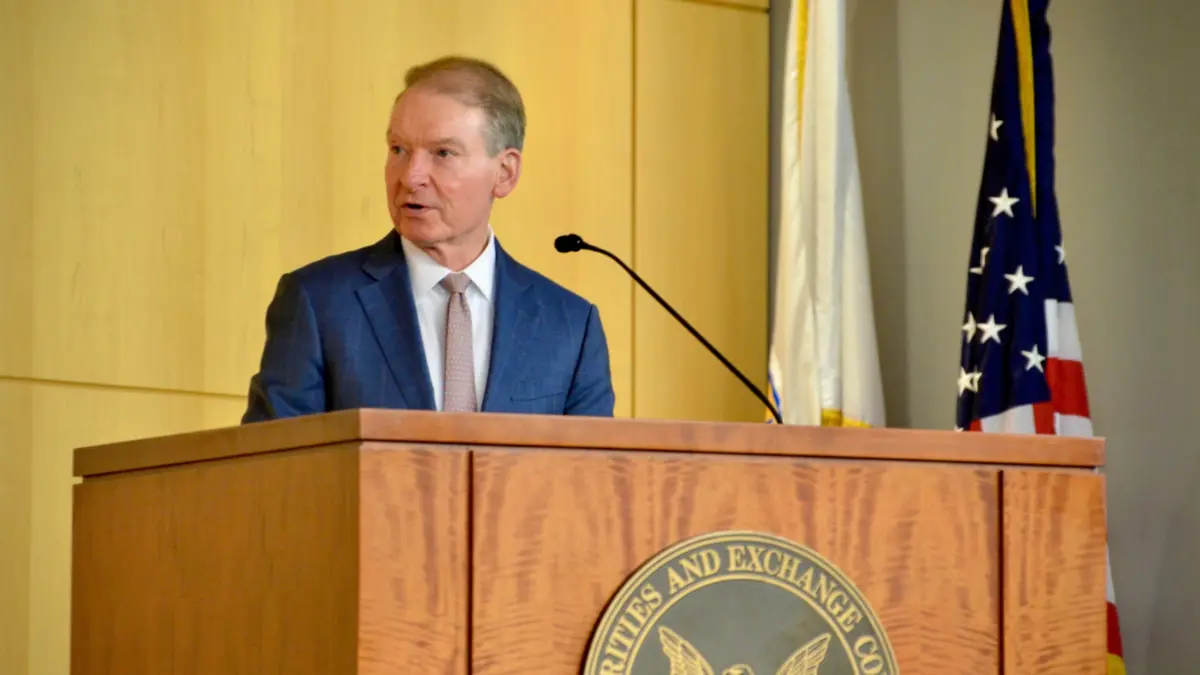
One of the more nuanced elements of the 760-page document involves the concept of "self-custody." The SEC’s proposal allows for a specific form of self-custody by investment advisers seeking to hold their clients’ funds directly. However, the agency was careful to distinguish its definition of the term from the one commonly used in the crypto community, where "self-custody" typically refers to an individual holding their own private keys.
In the context of the SEC proposal, self-custody refers to an asset management firm maintaining direct control over client assets rather than outsourcing that responsibility to a third-party qualified custodian. This pathway is not intended to be the standard practice, but rather a fallback option for specific, limited circumstances.
According to an SEC official, the ability for an investment firm to hold its own clients’ assets would be subject to strict prerequisites. First, the adviser must demonstrate that they were unable to find a qualified custodian ready and willing to take the assets. This situation might arise, for example, during the launch of a new or highly specialized token that established custodians do not yet support.
Furthermore, the investment firm must prove it possesses the technical expertise necessary to securely manage digital assets. Even if these conditions are met, the firm’s self-custody arrangement would be subject to a mandatory review every quarter. This recurring check is designed to determine if a qualified third-party custodian has since become available to take over the responsibility. The SEC official noted that while this provision stems from a direct request from the industry to the Crypto Task Force, it is expected to be an "unusual circumstance" once the broader custody market matures under the new rules.
Administrative Shifts and the Quorum Challenge
The timing of the proposal is inextricably linked to the shifting leadership at the SEC. With Commissioner Hester Peirce’s departure scheduled for Friday, the agency is facing a period of transition. Peirce’s exit to take up a professorship in Virginia will leave the SEC with only two active commissioners.
This looming vacancy prompted the SEC to take preemptive administrative action earlier this week. The agency moved to reduce the number of commissioners required to form a quorum. While the commission historically required at least three members to conduct official business and approve rules, the new internal guidelines allow for a quorum of just two.
The rule change also addresses potential conflicts of interest. If one of the two remaining commissioners is forced to recuse themselves from a specific action due to a conflict, the remaining single commissioner can now legally form a quorum to ensure the agency remains functional. This administrative shift ensures that the momentum of the current regulatory agenda—including the newly proposed custody rules—can continue even as the commission’s seats remain unfilled.