In a significant move aimed at modernizing the federal oversight of digital assets, the U.S. Securities and Exchange Commission (SEC) on Thursday proposed a comprehensive new regulatory framework governing how investment advisers and funds must handle and safeguard customer crypto assets. The 760-page proposal represents a fundamental shift in the agency’s approach, seeking to replace decades-old regulations with a structure specifically tailored to the unique technical and operational requirements of the blockchain era.
The proposal arrived as a cornerstone of the agency’s current agenda, serving as a legislative "swan song" for Commissioner Hester Peirce. Peirce, who has served as the inaugural chief of the SEC’s Crypto Task Force and has long been a vocal advocate for regulatory clarity in the digital asset space, is slated to exit the agency this Friday. Her departure marks the end of an era for the commission’s internal crypto policy development and comes at a time when the agency is moving rapidly to finalize a pro-crypto securities agenda.
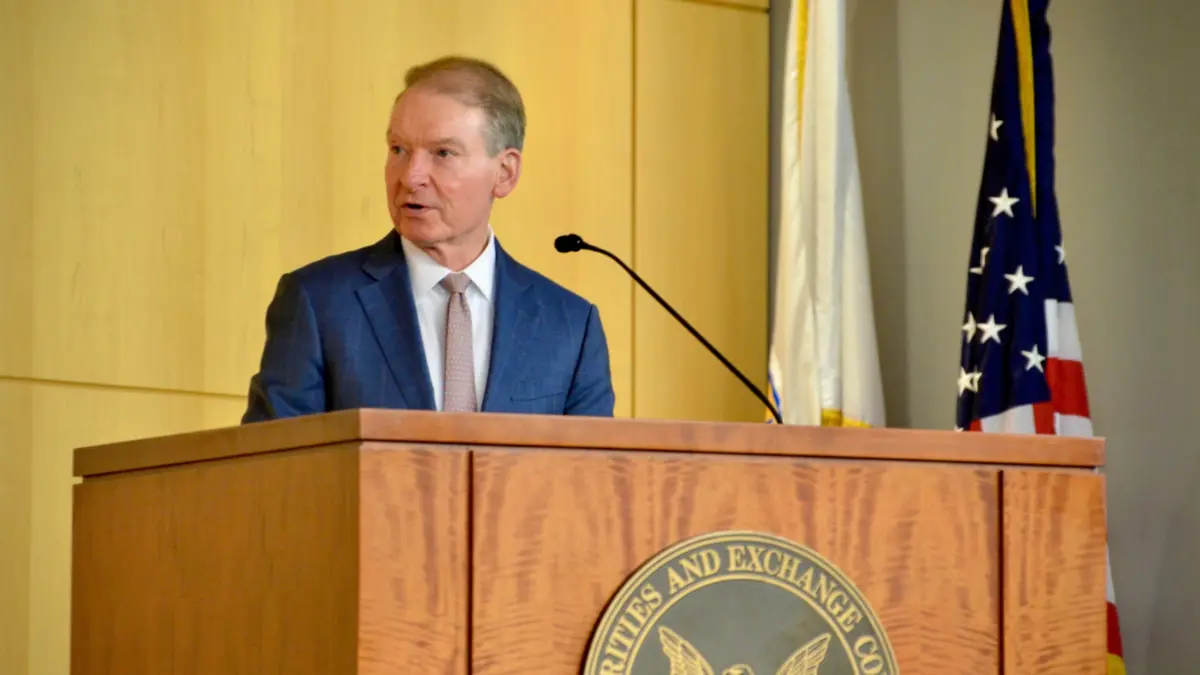
SEC Chairman Paul Atkins, in a statement accompanying the release of the proposal, framed the move as a necessary evolution of the agency’s protective mandate. He noted that while the primary goal of the SEC has always been to protect advisory clients and regulated funds from the loss, theft, or misuse of their assets, the existing rulebook was increasingly ill-equipped to handle the realities of the 21st-century financial landscape.
"The U.S. Securities and Exchange Commission is aiming to clarify how investment firms can handle and keep customer crypto assets in a new rule proposed Thursday," Atkins stated. "This proposal would provide a clear regulatory framework for the custody of crypto assets, giving investment advisers and funds a compliant pathway where none existed before—and replacing the grey of uncertainty created by custody rules crafted for a bygone era."
A New Standard for Digital Asset Safekeeping
The proposed rules seek to resolve years of ambiguity regarding which entities are legally permitted to hold crypto assets on behalf of institutional investors. Under the current regime, many investment advisers have struggled to find "qualified custodians" that meet the SEC’s traditional standards, often leading to a fragmented market where firms operated in a state of regulatory limbo.
The SEC’s new approach clarifies the specific categories of companies that can serve as proper custodians for crypto assets. Crucially, the proposal would formally permit the use of state-chartered trusts as custodians. This inclusion is a major development for the industry, as many of the most prominent crypto-native custody providers operate under state trust charters rather than national bank charters. By explicitly recognizing these entities, the SEC is opening a clear door for regulated funds to engage with established crypto infrastructure providers.
Beyond defining who can hold the assets, the proposal introduces rigorous new requirements for record-keeping and federal disclosures. Investment advisers would be required to maintain detailed logs of digital asset transactions and provide regular reports to the SEC, ensuring a level of transparency comparable to that of traditional equity and bond markets. The rules also introduce specific auditing requirements, designed to verify that the assets claimed by a fund actually exist on the blockchain and are under the exclusive control of the designated custodian.
The "Self-Custody" Exception for Advisers
One of the more nuanced elements of the 760-page document involves the concept of "self-custody." The SEC’s proposal allows for a specific form of self-custody by investment advisers seeking to hold their clients’ funds directly. However, the agency was careful to distinguish its definition of the term from the one commonly used in the crypto community, where "self-custody" typically refers to an individual holding their own private keys.
In the context of the SEC proposal, self-custody refers to an asset management firm maintaining direct control over client assets rather than outsourcing that responsibility to a third-party qualified custodian. This pathway is not intended to be the standard practice, but rather a fallback option for specific, limited circumstances.
According to an SEC official, the ability for an investment firm to hold its own clients’ assets would be subject to strict prerequisites. First, the adviser must demonstrate that they were unable to find a qualified custodian ready and willing to take the assets. This situation might arise, for example, during the launch of a new or highly specialized token that established custodians do not yet support.
Furthermore, the investment firm must prove it possesses the technical expertise necessary to securely manage digital assets. Even if these conditions are met, the firm’s self-custody arrangement would be subject to a mandatory review every quarter. This recurring check is designed to determine if a qualified third-party custodian has since become available to take over the responsibility. The SEC official noted that while this provision stems from a direct request from the industry to the Crypto Task Force, it is expected to be an "unusual circumstance" once the broader custody market matures under the new rules.
Administrative Shifts and the Quorum Challenge
The timing of the proposal is inextricably linked to the shifting leadership at the SEC. With Commissioner Hester Peirce’s departure scheduled for Friday, the agency is facing a period of transition. Peirce’s exit to take up a professorship in Virginia will leave the SEC with only two active commissioners.
This looming vacancy prompted the SEC to take preemptive administrative action earlier this week. The agency moved to reduce the number of commissioners required to form a quorum. While the commission historically required at least three members to conduct official business and approve rules, the new internal guidelines allow for a quorum of just two.
The rule change also addresses potential conflicts of interest. If one of the two remaining commissioners is forced to recuse themselves from a specific action due to a conflict, the remaining single commissioner can now legally form a quorum to ensure the agency remains functional. This administrative shift ensures that the momentum of the current regulatory agenda—including the newly proposed custody rules—can continue even as the commission’s seats remain unfilled.
The Broader Crypto Agenda
The custody proposal is the latest in a series of aggressive moves by the SEC to provide a comprehensive regulatory structure for the digital asset industry. With this announcement, the agency has now addressed nearly every major topic on the crypto agenda originally outlined by Chairman Atkins.
This push for clarity has included the recent publication of the "Innovation Exemption" for tokenizing securities. That framework provided a legal pathway for traditional financial institutions to issue and trade securities products, such as bonds or money market funds, directly on a blockchain. By allowing traditional assets to move into a digital format, the SEC laid the groundwork for the custody rules proposed on Thursday; if securities are tokenized, the industry requires a clear set of rules on how those tokens must be stored.
Additionally, the SEC previously introduced "Regulation Crypto Asset," a set of guidelines explaining how companies can conduct fundraising through digital asset offerings without violating federal securities laws. Together, these three pillars—fundraising, tokenization, and custody—form the backbone of what Atkins has described as a "pro-crypto U.S. securities agenda."
Next Steps and Public Comment
As is standard with major SEC rule-making, the proposed custody framework is now subject to a 60-day public comment period. This window allows industry participants, legal experts, and the general public to submit feedback, which the commission will review before moving toward a final vote.
The proposal has been met with immediate interest from the digital asset sector, which has long argued that the lack of clear custody rules was a primary barrier to institutional adoption of crypto in the United States. By providing a "compliant pathway" for investment advisers and funds, the SEC is signaling that it views digital assets as a permanent fixture of the financial system, requiring a regulatory environment that is both rigorous and technically informed.
The departure of Hester Peirce marks a significant moment for the Crypto Task Force, but the publication of this 760-page proposal suggests that her influence on the agency’s direction will persist. As the industry begins its deep dive into the technical requirements of the new rule, the focus shifts to how quickly the SEC can move from a proposal to a finalized, enforceable standard that will govern the next generation of asset management.