The collapse of the Digital Asset Market Clarity Act in the United States Senate has left a significant vacuum in the nation’s financial regulatory framework, but federal agencies are not waiting for a legislative resurrection. In the wake of the bill’s failure, the U.S. Securities and Exchange Commission (SEC) and the Commodity Futures Trading Commission (CFTC) have embarked on an aggressive, high-stakes race to substitute internal agency rulemaking for the statutory bedrock that Congress failed to provide.
For years, the Digital Asset Market Clarity Act was viewed by many in the industry as the definitive solution to a decade of jurisdictional infighting and "regulation by enforcement." The legislation was designed to provide a comprehensive taxonomy for digital assets, clearly demarcating which tokens fall under the SEC’s securities oversight and which belong to the CFTC’s commodities domain. Its failure to pass has forced a pivot: instead of a unified law, the industry is now facing a piecemeal regulatory landscape built on the personal initiatives of agency leaders.
The Clarity-Shaped Hole in U.S. Policy
The Digital Asset Market Clarity Act was the latest and perhaps most robust attempt by Congress to define the different categories of cryptocurrencies and blockchain-native assets. For the better part of the last decade, the U.S. crypto sector has been defined by a state of perpetual conflict with federal regulators. Under previous leadership, most notably former SEC Chair Gary Gensler, the agency pursued a flurry of enforcement actions against major platforms like Coinbase and Kraken. The central point of contention was almost always whether the issuance and trading of digital assets were legally indistinguishable from the launching of traditional securities.
This friction led to expensive settlements, high-profile court battles, and a general sense of domestic stagnation as firms looked toward more unified regulatory regimes in Europe and Asia. The Clarity Act promised to end this era by establishing "rules of the road" that would have elevated the CFTC to a more prominent role. Most significantly, it would have granted the CFTC full supervisory powers over crypto commodity spot markets—the venues where assets like Bitcoin and Ethereum are traded directly.
In the current U.S. system, the regulation of spot markets for commodities is largely absent a hands-on federal overseer, except in cases of fraud or market manipulation. Since Bitcoin and Ether were eventually determined to be commodities rather than securities, a massive portion of the crypto market has existed in a regulatory gray zone. The Clarity Act aimed to fill this gap, while also introducing measures to curb illicit finance and provide limited legal protections for software developers working in decentralized finance (DeFi). The goal was to ensure that developers would not be held liable for how third parties chose to use their open-source protocols.
When the Senate vote failed, that vision of a legislative "bedrock" vanished. However, the agencies responsible for the sector did not pause to mourn.
The SEC’s Aggressive Pivot Under Paul Atkins
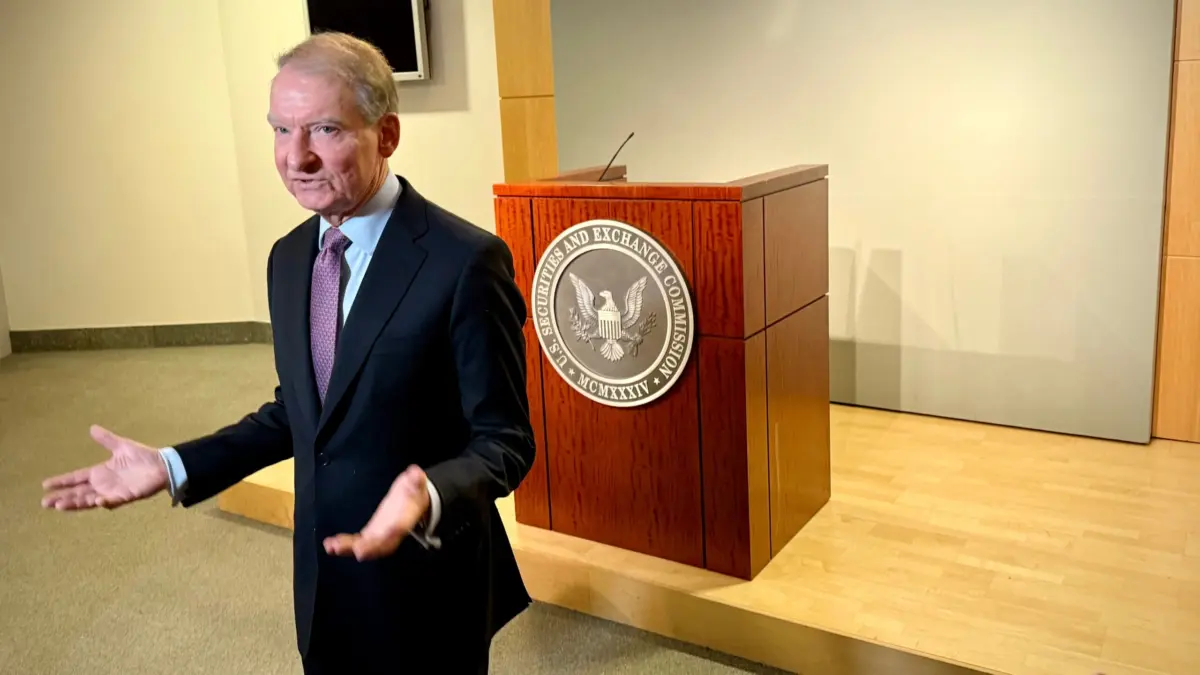
Leading the charge to fill the legislative void is SEC Chairman Paul Atkins. A Trump appointee and a known proponent of digital asset innovation, Atkins has wasted no time in asserting the SEC’s authority to shape the market through internal policy rather than waiting for a new congressional mandate.