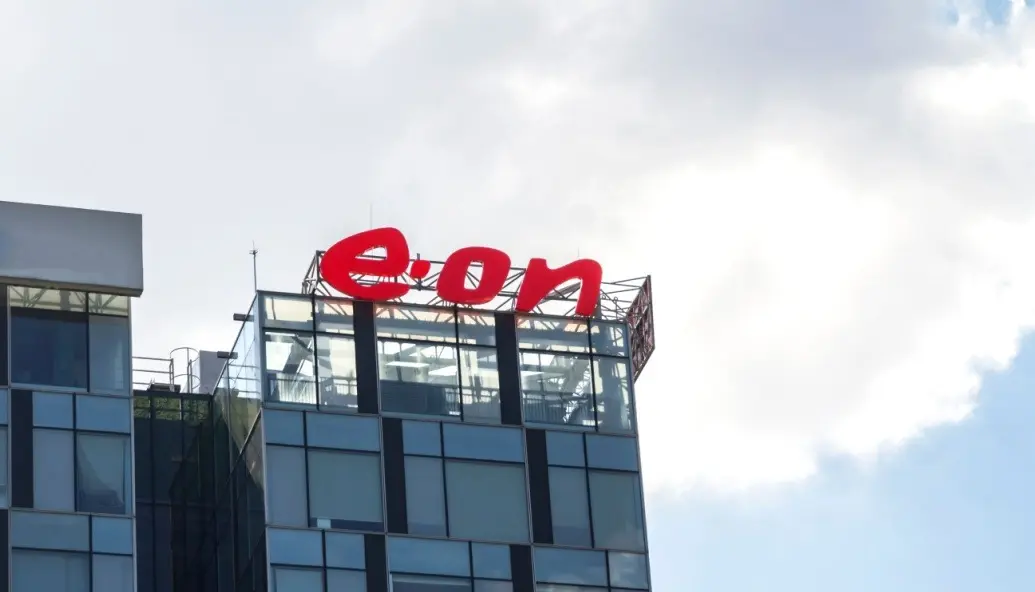
The implications of this merger extend far beyond the two companies involved, as it fundamentally redraws the competitive map of the UK energy retail market. The union of E.ON and OVO is a defining moment in the transition from the traditional "Big Six" model to what many analysts are now describing as the "Big Three." Following this acquisition, the domestic market is now heavily concentrated among three major players: Octopus Energy, British Gas, and the newly expanded E.ON. Together, these three giants now control an estimated 74% of the domestic energy market, a level of concentration that has not been seen in the UK for decades.
This consolidation is the culmination of a decade of intense market turbulence. For years, the UK government and regulators encouraged a "challenger" model, where smaller, independent suppliers were expected to break the dominance of established legacy providers. However, the energy crisis of the early 2020s, characterized by record-high wholesale gas prices and a series of supplier failures, fundamentally altered that trajectory. The market has since pivoted toward larger, more resilient entities capable of absorbing economic shocks and funding the massive investments required for the transition to net-zero emissions.

OVO’s journey to this point is particularly noteworthy. Originally founded as a "challenger" brand that aimed to disrupt the established order with a focus on technology and customer service, OVO grew rapidly, eventually acquiring the retail arm of SSE. Its integration into E.ON represents the final chapter of that independent growth story, as it joins one of Europe’s largest energy operators. For E.ON, the acquisition provides a wealth of digital expertise and a customer base that has traditionally been more engaged with green energy solutions and smart home technologies.
The move toward a "Big Three" structure raises important questions about the future of competition and innovation in the UK energy sector. While the CMA has provided its initial clearance, the long-term impact on pricing and consumer choice remains a subject of intense interest for industry observers. Proponents of the merger argue that larger companies are better equipped to invest in the smart grids, heat pumps, and electric vehicle charging infrastructure necessary for the energy transition. Scale, in this view, provides the financial "firepower" needed to drive down the costs of new technologies through bulk procurement and integrated service delivery.
On the other hand, the high level of market concentration—with three firms holding nearly three-quarters of the market—puts a significant responsibility on those companies to maintain high standards of service and fair pricing. With the "Big Three" now holding such a dominant position, the role of the regulator, Ofgem, will become even more critical in ensuring that the benefits of scale are passed on to the consumer rather than merely serving to bolster corporate margins.