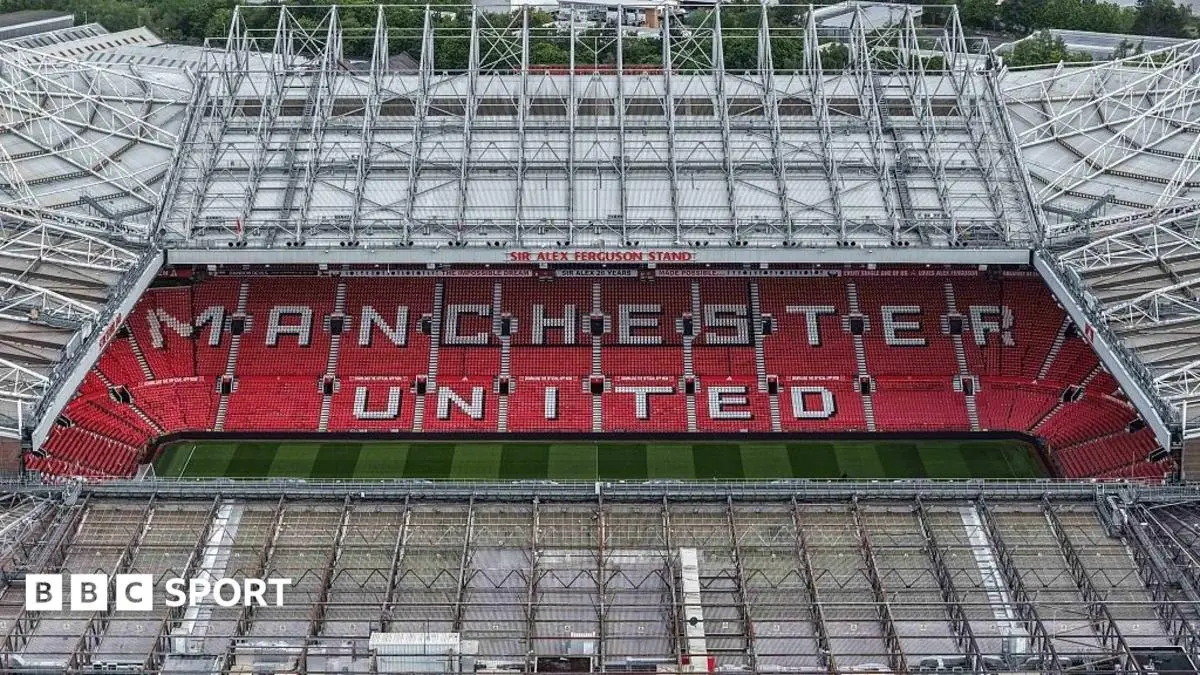
Manchester United have secured an additional £90 million in debt since the end of June, according to detailed financial disclosures. The Premier League club has also confirmed that its total expenditure on new player acquisitions during the summer transfer window reached £191.7 million. These latest financial revelations paint a complex picture of the club’s ongoing economic challenges, balancing high-stakes squad investment with a mounting debt burden.
The updated financial figures were detailed in a comprehensive filing submitted to the New York Stock Exchange on Thursday. This regulatory filing followed the release on Wednesday of Manchester United’s annual accounts for the 2025-26 financial year ending June 30. Together, the documents reveal that the club’s overall debt still exceeds the £1 billion threshold, standing at a substantial £1.15 billion, despite the sweeping cost-cutting initiatives introduced by minority owner Sir Jim Ratcliffe since his arrival in 2024.
A major portion of the financial update centers on Manchester United’s activity in the transfer market, where the club was highly active. During the summer window, United secured several high-profile additions to their squad. On July 13, the club finalized the purchase of Andrey Santos from Chelsea. This was quickly followed on July 14 by the acquisition of midfielder Youri Tielemans from Aston Villa. Later in the window, on August 25, the club completed a deal for Carlos Baleba from Brighton.
At the time these individual transfers were announced, the cumulative fees reported for the trio of Santos, Tielemans, and Baleba amounted to £153 million. However, the club’s latest financial filings state that the actual total expenditure on summer signings was £191.7 million. This leaves an unexplained difference of £38.7 million between the initially reported individual transfer fees and the final figure confirmed in the financial documents. It remains unclear where or how this additional sum was allocated, and Manchester United have been approached for comment regarding the discrepancy.
The detailed filing on Thursday also shed light on the club’s recent borrowing activities, confirming a net increase of £90 million in debt since June 30. This increase was driven by active utilization of the club’s revolving credit facilities. United confirmed that it made three separate drawdowns from its revolving credit limit over the summer months to manage its short-term cash flow needs.
The first two drawdowns occurred in quick succession on July 29 and July 31, followed by a third drawdown on August 28. Combined, these three transactions saw the club draw down a total of £120 million from its credit line. Subsequently, on September 21, Manchester United made a repayment of £30 million, resulting in the net borrowing figure of £90 million for the period following the close of the financial year on June 30.
These recent transactions have pushed Manchester United’s total outstanding debt to a staggering £1.15 billion. The overall debt structure is composed of three primary elements: the club’s long-standing historic debt, outstanding balances on its revolving credit facility, and unpaid transfer fees owed to other football clubs.
The historic debt, which has been a feature of the club’s balance sheet since the leveraged buyout by the Glazer family in 2005, currently stands at £578 million. This legacy debt continues to incur significant interest costs and remains a central point of discussion regarding the club’s financial health. In addition to this historic sum, Manchester United owe £200 million on their revolving credit facility, reflecting the recent summer drawdowns and repayments.
The third component of the club’s overall debt is £375 million in outstanding transfer fees. This represents the money Manchester United owe to other clubs for player transfers that were structured with deferred payment terms. While this is a significant liability, the latest figures show a £72 million reduction compared to the £447 million that was owed in outstanding transfer fees in the club’s 2024-25 accounts.
Despite this year-on-year reduction, the outstanding transfer debt remains a substantial near-term financial obligation. A detailed breakdown of the repayment schedule reveals that a significant portion of this money must be paid in the very near future. The majority of the £375 million—specifically, the remainder after future allocations are subtracted—is due to be paid within the next 12 months.
Looking further ahead, the club’s financial filings indicate that £104.8 million of the outstanding transfer fees is scheduled for payment in between one and two years. A further £51.9 million is due to be settled in the period between two and five years. To manage these substantial future cash outflows, Manchester United have stated that payments for their most recent player transfers "are due within the next five years," allowing the club to spread the financial impact of their summer recruitment drive over a longer period.
The persistence of a debt pile exceeding £1.1 billion highlights the immense financial challenges facing the club, even as it undergoes a major internal restructuring. Since billionaire industrialist Sir Jim Ratcliffe acquired a minority stake in the club in 2024, his INEOS team has implemented a series of aggressive cost-cutting measures designed to streamline operations and improve financial efficiency.
These measures have included a significant reduction in staff numbers, with hundreds of redundancies across various departments, alongside a thorough review of corporate expenses and operational overheads. The goal of these cuts has been to ensure the club complies with the Premier League’s strict Profit and Sustainability Rules (PSR) while maximizing the resources available for investment in the first-team squad.
However, the latest financial disclosures demonstrate that internal operational savings alone are not enough to offset the massive capital requirements of competing at the highest level of European football. The necessity of maintaining a competitive squad has required continued heavy investment in the transfer market, as evidenced by the £191.7 million spent on Santos, Tielemans, Baleba, and other potential undisclosed outlays this summer.
This tension between operational cost-cutting and heavy capital expenditure on players explains why the club has had to rely so heavily on its revolving credit facility. The drawdowns in July and August coincided directly with the peak of the summer transfer window, a period when clubs must often make substantial upfront payments or secure bank guarantees to finalize high-profile signings before the season begins.
By utilizing the revolving credit facility, Manchester United can bridge the gap between immediate transfer outlays and the receipt of major seasonal revenues, such as broadcast distributions, sponsorship payments, and matchday income, which are typically distributed throughout the course of the season. The £30 million repayment made on September 21 suggests that as some of these seasonal revenues began to flow into the club, management immediately moved to reduce their short-term borrowing.
The detailed reporting required by the New York Stock Exchange provides a rare level of transparency into the financial mechanics of a major football club. While most Premier League clubs only publish their accounts annually, Manchester United’s status as a publicly traded company on the NYSE subjects them to rigorous quarterly reporting standards. This allows observers and investors to track the club’s cash flow, borrowing habits, and transfer liabilities in real-time, offering a clear view of the financial balancing act required to run one of the world’s largest sporting institutions.
Ultimately, the latest figures underscore that despite a change in sporting leadership and a renewed focus on fiscal discipline, Manchester United remain heavily reliant on debt to fund their operations and transfer ambitions. With £375 million still owed to other clubs and a total debt of £1.15 billion, the financial strategy under the new regime will continue to require careful management to balance the demands of on-pitch success with the realities of a highly leveraged balance sheet.