This prioritization of Asian markets is a reflection of the long-term strategic shift in Saudi energy policy, which views the Asia-Pacific region as the primary engine of global demand growth. By ensuring that Asian customers remain supplied despite the domestic infrastructure crisis, Saudi Aramco is protecting its most valuable market share and maintaining its reputation as a reliable partner in the East. However, this "Asia-first" approach leaves European refiners in a precarious position. Because the crude is being exported from the Persian Gulf rather than the Red Sea, any shipments intended for Europe would face a significantly more arduous and expensive journey.
For a tanker to reach Europe from Ras Tanura, it must first navigate the Strait of Hormuz, then travel around the Arabian Peninsula and through the Bab el-Mandeb strait into the Red Sea to reach the Suez Canal. This route is not only longer but also fraught with security risks, particularly in the southern Red Sea where maritime traffic has faced persistent threats. The alternative is even more daunting: sailing the entire length of the African continent and rounding the Cape of Good Hope. This route adds thousands of miles and several weeks to the journey, dramatically increasing shipping costs and tying up tanker capacity for longer periods. Given these logistical hurdles, the decision to zero out European allocations appears to be a pragmatic, albeit painful, acknowledgment that supplying the West from the Persian Gulf is currently inefficient compared to serving the Asian market.
The impact on European crude markets is already becoming evident as traders and refiners digest the news. The sudden removal of millions of barrels of Saudi crude from the October balance sheet adds immense pressure to an already strained regional supply chain. Europe has been navigating a complex energy landscape for several years, characterized by the transition away from Russian energy and a heightened reliance on seaborne imports from more distant suppliers. The loss of Saudi volumes, which are typically stable and reliable, introduces a new layer of volatility. Refiners in Northwest Europe and the Mediterranean are now forced to compete for available "sweet" and "medium-sour" grades in the spot market, which is likely to drive up the premiums for regional benchmarks like Brent.
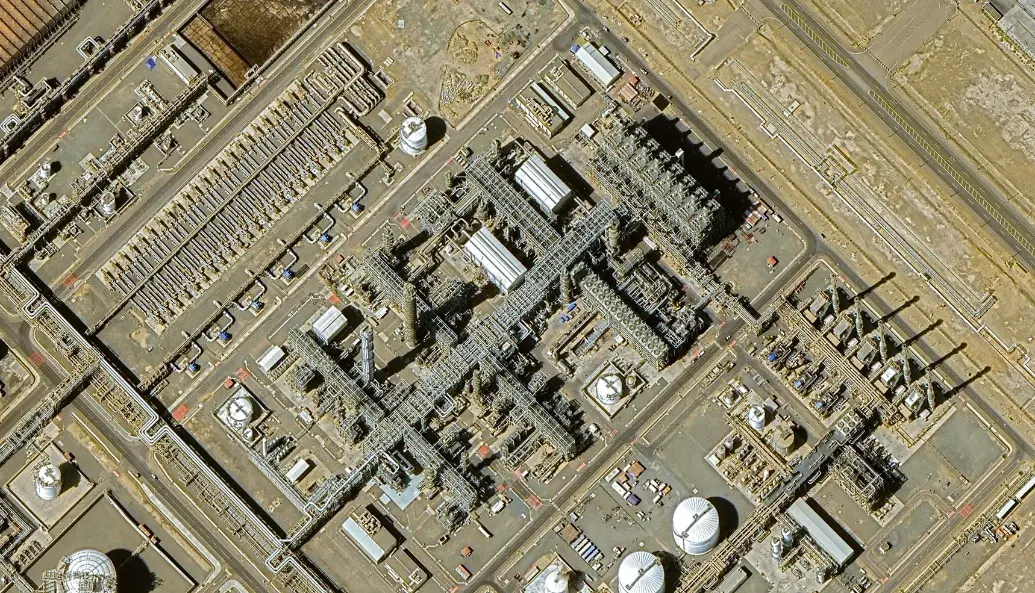
Furthermore, the disruption highlights the continued impact of regional conflict on global energy security. The strikes on Saudi energy facilities, which targeted the nodes of the East-West pipeline, demonstrate that even the most robust and strategically defended infrastructure is vulnerable to asymmetric threats. For the global oil market, the incident serves as a stark reminder that the "bypass" routes designed to ensure the free flow of energy are just as susceptible to disruption as the maritime choke points they were built to avoid. The fact that Saudi Arabia, the world’s preeminent swing producer, is forced to cut off term customers in a major economic bloc like Europe illustrates the severity of the physical damage to its network.