The decision to halt supplies to Europe appears to be a systemic response to the operational constraints currently facing the Saudi energy apparatus. According to reports from industry observers and trade publications, including OilPrice.com, at least two major European refiners have already been notified that their expected allocations for October will be non-existent. Market analysts suggest that this policy is not being applied selectively but is instead expected to be enforced across the board for all European term buyers who rely on consistent, contractually obligated volumes of Saudi crude. The move underscores the severity of the damage to the East-West pipeline, which serves as a vital strategic bypass for the kingdom’s oil exports, allowing them to reach western markets without navigating the increasingly volatile waters of the Persian Gulf.
To understand the magnitude of this disruption, one must consider the strategic role of the East-West pipeline, often referred to as the Petroline. This massive infrastructure project spans approximately 1,200 kilometers across the Arabian Peninsula, connecting the prolific oil fields in the Eastern Province—most notably the Ghawar field—to the port of Yanbu on the Red Sea coast. Under normal operating conditions, the pipeline has the capacity to transport between four and five million barrels of crude oil per day. By moving oil to Yanbu, Saudi Arabia can load tankers that have immediate access to the Suez Canal and the Mediterranean, effectively bypassing the Strait of Hormuz. The Strait of Hormuz is a notorious maritime choke point that is frequently subject to geopolitical tensions and threats of closure, making the Petroline the primary insurance policy for Saudi Arabia’s westward-bound energy exports.
The damage to this pipeline, which follows recent strikes attributed to Houthi forces, has effectively severed this western exit route. With the pipeline incapacitated or operating at a severely diminished capacity, the crude that would normally flow to Yanbu is essentially stranded in the eastern part of the country. For European refiners, who have calibrated their facilities to process specific grades of Saudi crude—such as Arab Light and Arab Extra Light—the sudden disappearance of these volumes presents an immediate logistical and economic challenge. These refiners must now look to the spot market to fill the void, likely turning to more expensive or less compatible grades from the North Sea, West Africa, or the United States, all of which carry higher freight costs and different chemical profiles that can affect refining margins.
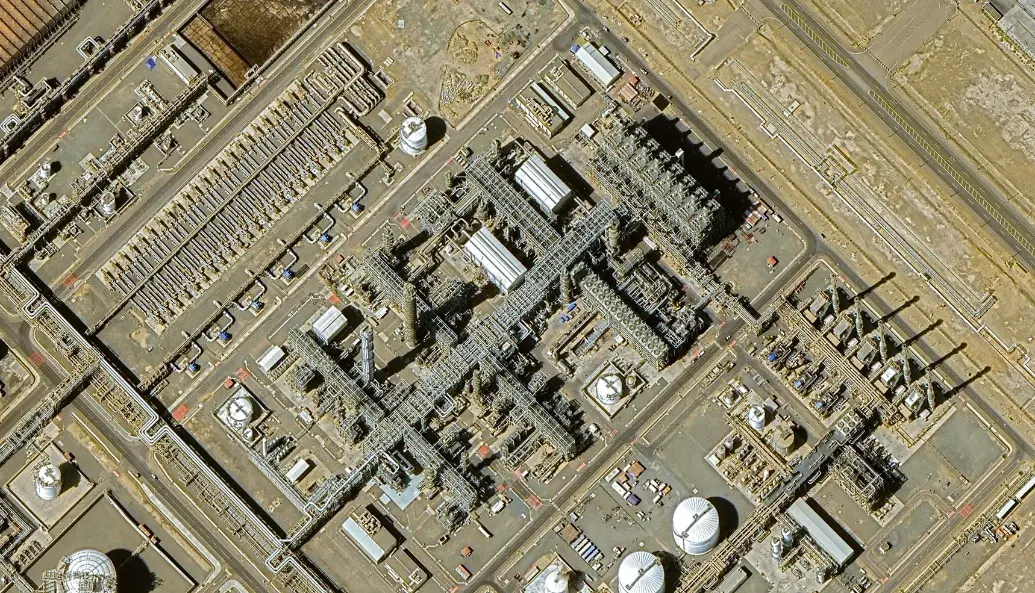
While Saudi Aramco has reportedly sought ways to mitigate the impact of the pipeline disruption, the solutions implemented thus far have offered no relief to the European market. Instead, the kingdom has pivoted its focus toward its eastern export terminals. Reports indicate that Saudi Arabia has begun the massive logistical undertaking of moving approximately 60 million barrels of crude from its primary Persian Gulf export terminal at Ras Tanura. Ras Tanura is the world’s largest offshore oil loading facility, and it remains the heart of the Saudi export machine. However, the crude being loaded at this terminal is not being redirected to the West to make up for the shortfall in Yanbu. Instead, these additional supplies are being prioritized for Asian buyers, including major industrial economies such as China, South Korea, India, and Japan.