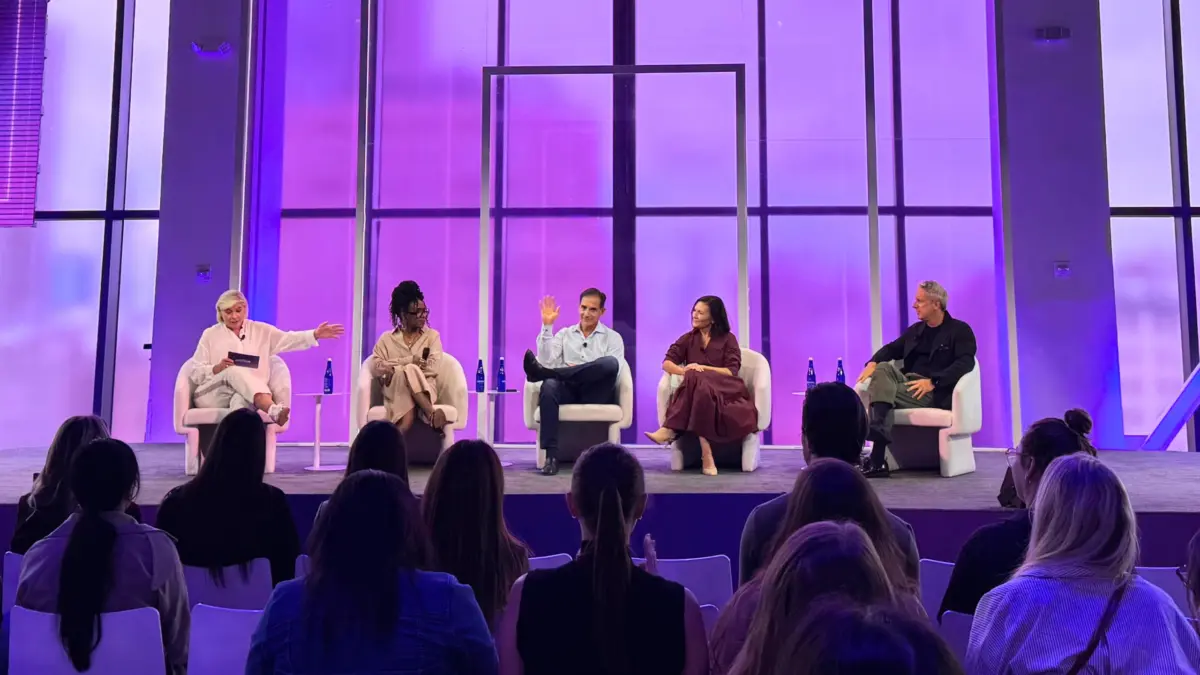
Lord, who leads the largest independent media agency in the world, focused his critique on the full-time equivalent (FTE) model and principal-based buying strategies. These methods, which are central to how the industry’s major holding companies generate revenue, are increasingly at odds with the modern technological landscape, according to Lord. He argued that the industry is currently caught in a state of "inertia," where the desire to maintain legacy profit margins is preventing the adoption of more agile, growth-oriented frameworks.
The core of the issue, as Lord presented it, lies in the "economic equation" that governs the relationship between an agency’s internal investments and the services they provide to their clients. Over the past half-decade, the industry has seen a massive influx of capital into proprietary technology, data platforms, and automation tools. However, Lord suggested that instead of these tools being used to streamline costs or create more value for the brand, they are being leveraged to justify old billing practices. He noted that agencies, particularly the large holding companies, have made significant investments in technology over the last five years and now feel a structural pressure to monetize those investments by forcing them onto their client base.
This dynamic, Lord argued, creates a conflict of interest where the agency’s need to recoup its technology costs overrides the client’s need for the most efficient and effective growth strategies. He specifically pointed to the FTE-based model, where clients pay for the hours of staff members assigned to their accounts, as a primary culprit. In an era where automation and advanced software can handle tasks that once required dozens of human hours, the continued reliance on hourly billing creates a disincentive for agencies to become more efficient. If an agency becomes twice as fast at a task through technology, a labor-based model would theoretically result in the agency making half as much money, unless they find other ways to bill for that time.
To move past this stagnation, Lord advocated for the adoption of "composable architectures." This approach involves moving away from monolithic, "one-size-fits-all" technology stacks in favor of modular, interoperable systems that can be customized to drive specific business outcomes. By utilizing composable architectures, agencies and brands can be more selective about the tools they use, ensuring that every piece of the technological puzzle is directly contributing to growth rather than simply serving as a line item in a broader service agreement.
The shift toward these modular systems is not just a technological preference but a business necessity. Lord’s comments suggested that the current model is a barrier to the very growth that clients are hiring agencies to achieve. When agencies are locked into rigid billing structures and proprietary tech stacks that they must "force" on clients to maintain their own P&Ls, the focus shifts from the client’s market performance to the agency’s internal financial requirements.
Lord was careful to clarify that his observations were not an attack on specific competitors, but rather an analysis of the structural economics of the advertising business. He stated he was "not picking on anyone" specifically, but was instead highlighting a fundamental flaw in the industry’s current trajectory. This "economic equation" is what Lord believes will eventually force the hand of every major player in the space.
The most striking part of Lord’s presentation was his timeline for this transformation. He predicted that within the next five years, the industry will reach a breaking point where clients will simply stop paying for the FTE model. This five-year window suggests a rapid acceleration of trends that have been bubbling under the surface for years. As brands become more sophisticated in their understanding of data and technology, and as procurement departments become more rigorous in their evaluation of agency value, the transparency and efficiency of the FTE model are being called into question.
The prediction of the FTE model’s demise carries significant implications for the global holding companies—WPP, Publicis, Omnicom, Interpublic, and Dentsu—which have built their empires on the scale of their workforces and the volume of hours billed. If the industry shifts toward outcome-based or value-based pricing, these giants will have to fundamentally restructure how they value their services and how they demonstrate their worth to shareholders.
Lord also touched upon "principal-based buying" as another pillar of the "old system" that is ripe for disruption. In a principal-based model, an agency buys media inventory in bulk from publishers and then resells it to its clients, often at a markup or with associated fees that may not be fully transparent. While this can sometimes offer clients lower rates due to the agency’s scale, Lord’s critique suggests that it is often used as a mechanism to bolster agency margins and justify the high costs of their internal technological infrastructures.
The conversation in Lower Manhattan took place against a backdrop of broader industry soul-searching. As the advertising world prepares for major upcoming gatherings, such as the ADWEEK House event in Midtown Manhattan this October, the tension between traditional agency models and the needs of modern commerce remains a central theme. The industry is currently at a crossroads, where the "inertia" Lord described is being challenged by the rapid development of artificial intelligence and the increasing demand for measurable business results over simple media impressions.
Horizon Media’s position as an independent agency gives Lord a unique vantage point. Without the same pressures from a parent holding company to maintain specific margin structures across dozens of different subsidiary agencies, independents often have more flexibility to experiment with new billing models and technology partnerships. Lord’s advocacy for composable architectures reflects this desire for flexibility, suggesting that the future of the industry belongs to those who can pivot quickly and align their financial success directly with the success of their clients.
For clients, the message from Lord is one of empowerment but also one of caution. While the end of the FTE model may lead to more efficient and transparent relationships, it also requires brands to take a more active role in defining what they are paying for. If they are no longer paying for "hours," they must become experts at paying for "value," which requires a deep understanding of the technology and data that drive modern marketing.
The shift Lord describes is not merely a change in accounting but a change in the philosophy of partnership. In the old system, the agency was a vendor of labor; in the new system envisioned by Lord, the agency must be an architect of growth, using technology not as a way to hide costs, but as a transparent engine for business expansion.
As the industry looks toward the next five years, the "inertia" Lord identified will likely be tested by market forces. If his prediction holds true, the agencies that survive and thrive will be those that can successfully transition away from selling human time and toward selling technological and strategic expertise. The move to composable architectures and the abandonment of the FTE model represent more than just a change in business tactics—they represent a total reimagining of the economic bond between those who create advertising and those who pay for it.
With the Smartly Advance event serving as a platform for these candid reflections, the industry is left to consider how it will respond to Lord’s "economic equation." The five-year countdown to the end of the FTE model has effectively begun, and the pressure is on for agencies of all sizes to prove that they can deliver growth without relying on the billable hour. As the conversations continue into the fall and beyond, the focus will remain on whether the industry can overcome its own inertia before the market makes the decision for it.